Privacy-first · no signup
Commercial Rent Invoice Generator
Generate a commercial rent tax invoice or plain receipt — forward charge, RCM, or nil, based on your registration status. Auto-computes GST and TDS.
— No app to install · no sign-up · your document data stays in your browser.
Commercial rent — GST + TDS quick guide
Part of: Salary, Rent & Income-Tax Documents →
Related generators
What this generates
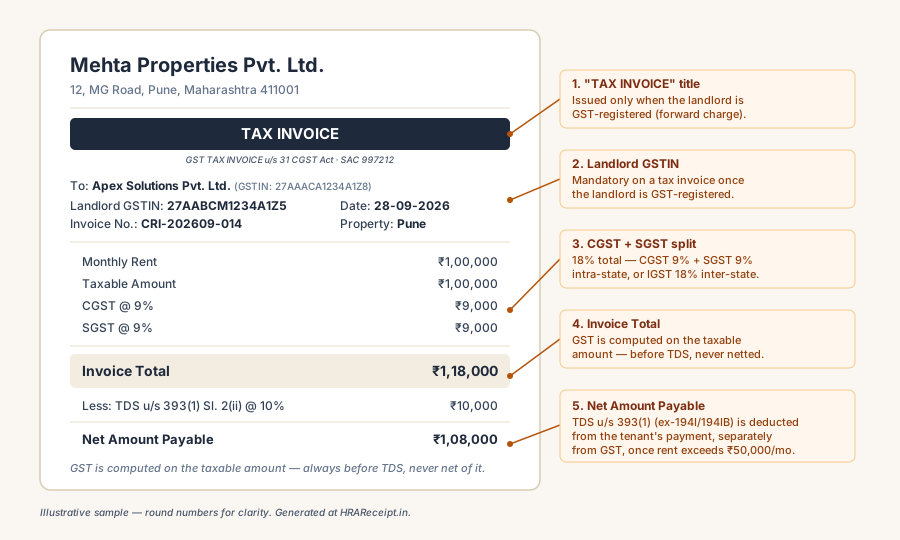
- TAX INVOICE (forward charge) or plain COMMERCIAL RENT RECEIPT (RCM/nil)
- GST @ 18% — CGST 9% + SGST 9% intra-state or IGST 18% inter-state
- SAC 997212 — non-residential / commercial immovable property
- RCM note (Entry 5AB, Notification 09/2024-CTR) when applicable
- TDS section (Section 393(1), formerly 194I / 194IB), rate, and net payable
- Amount in words + optional business letterhead
Primary sources
Document details
Invoice number, date, and the rented property.
Full address of the commercial premises being rented.
e.g. "July 2026" or "01/07/2026 to 31/07/2026"
How to generate a commercial rent invoice
- Enter the invoice number, date, rented property address, and rent period.
- Enter landlord and tenant details — landlord GSTIN is required only when GST-registered.
- Enter the monthly rent and registration status; GST and TDS compute automatically.
- Review the free on-page preview, then pay ₹5 for the final PDF.
Your invoice data is processed entirely in your browser — party names, GSTINs, rent, and tax figures never reach our servers. We do not store, log, or share your document data.
A commercial rent document carries two independent obligations: GST at 18% under forward charge or reverse charge (RCM) (RCM on rent does not apply to composition-scheme tenants), depending on which party is GST-registered; and TDS under Section 393(1) of the Income-tax Act, 2025 (Table Sl. No. 2 — formerly Sections 194-I/194-IB of the 1961 Act) once rent exceeds ₹50,000 for a month or part of a month, deducted separately from GST and never netted against it. TDS on rent (Section 393, formerly 194-IB) — full guide →
FAQ
Commercial rent invoice — common questions
What GST rate applies to commercial rent in India?
What is the reverse charge on commercial rent (Entry 5AB)?
When is TDS applicable on commercial rent?
Is GST computed on rent before or after TDS?
What document does the landlord issue under RCM?
What is SAC 997212?
References
After you generate
- PDF downloads to your device — your document content is never stored on our servers
- Forward-charge PDF is your Section 31 tax invoice — keep it for GST returns
- RCM case: give the plain receipt to your tenant; they self-invoice u/s 31(3)(f)
First-timer questions
When does RCM apply to commercial rent?
When the landlord is GST-unregistered and the tenant is GST-registered and has NOT opted for the composition levy — Notification 07/2025-CT(Rate) (w.e.f. 16.01.2025) excludes composition-scheme tenants from RCM on commercial rent (Entry 5AB). Entry 5AB (Notification 09/2024-CTR, w.e.f. 10.10.2024) requires the (non-composition) tenant to pay 18% GST under RCM and self-invoice under Section 31(3)(f).
Does GST apply if both parties are unregistered?
No. If both the landlord and tenant are unregistered, no GST is applicable. The document is a plain commercial rent receipt with no tax lines.
Is TDS on rent assessed monthly or annually?
Monthly — effective 01.04.2025 (Finance Act 2025), now under Section 393(1), Income-tax Act 2025 (formerly Sections 194-I/194-IB). TDS triggers when rent for a month (or part of a month) exceeds Rs. 50,000. The old annual Rs. 2.4 lakh limit was replaced.
Can I use this document for GST filing?
For forward-charge invoices: yes, it is a Section 31 tax invoice when all Rule 46 fields (incl. recipient GSTIN) are filled, and it can be used for GSTR-1 reporting. For RCM: the landlord's plain receipt is a supporting document; you (the tenant) must issue a self-invoice for ITC purposes.
Last reviewed: 28 September 2026